


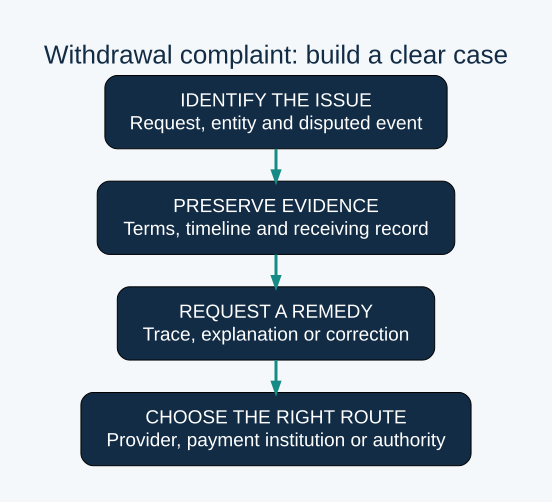
A broker withdrawal complaint should identify the request, explain the unresolved obligation and ask for a concrete remedy. A factual timeline is more useful than an unsupported accusation: it helps separate platform review, missing documents, payment release and receiving-account credit.
This guide supplies an evidence checklist, worked example and complaint template. Official UK and Indian sources were checked on 24 October 2026. Their complaint systems have defined eligibility; neither is a worldwide refund service for every platform using the word broker.
Define the withdrawal problem before making the complaint
Choose the disputed event: rejection without an adequate reason, an exceeded processing period, completion without receipt, an unexpected deduction or an account restriction. These need different evidence and requests.
“My request has shown pending since [date]” is an observation. “All withdrawals are fraudulent” is a much broader allegation that one record cannot establish. State what you can prove, what the provider has said and which fact remains unresolved.
| Issue | Focused remedy to request |
|---|---|
| Still under review | Identify the outstanding requirement and applicable processing rule. |
| Marked completed, no credit | Provide release evidence and an appropriate payment reference. |
| Rejected or cancelled | Explain the reason and reconcile any balance reversal. |
| Lower amount received | Itemise deductions, conversion and amount sent. |
| Destination restriction | Identify the relevant clause and authorised resolution. |
Build a compact withdrawal complaint evidence pack
- Contractual entity, actual domain and privately retained account identifier.
- Withdrawal ID, amount, currency, destination type and submission confirmation.
- Each status change with date, time and timezone where available.
- The relevant dated payment terms, including the stage covered by any estimate.
- Verification notices, upload confirmations and review decisions.
- Release evidence, external reference and receiving statement if applicable.
- Support replies and case numbers in chronological order.
Use an index so a reviewer can connect each attachment to a specific statement. For example, E1 is submission confirmation, E2 the processing clause and E3 the receiving record. Keep original files and redacted copies separate.
Do not edit an original screenshot to make its meaning stronger. Add annotations on a separate copy and preserve the full context privately. A cropped image can omit a currency, date or warning that changes the interpretation.
“Completed” in a dashboard and credit at the recipient are separate observations
Educational evidence comparison. Regulatory dates are sourced; any app or payment examples are fictional and are not real platform screenshots.
A. Fictional status-versus-receipt case
Preserve the request ID, amount, currency and payment method.
This records the provider’s displayed status, not independent receipt.
Retain the dated recipient-side record and note its coverage.
The difference requires investigation; this invented sequence does not establish fraud, a guaranteed deadline or the cause of a delay.
B. Ask a traceable question
Request the payment reference, destination, processing timestamp and current trace status.
Compare requested, deducted and received amounts in their recorded currencies.
Use the genuine complaint route and confirm the applicable process.
A receiving record with no matching credit documents what was checked. It does not automatically prove the sender never initiated payment.
No complaint is submitted by this visual. Keep originals private and publish redacted copies only where appropriate. A clear evidence packet supports investigation; it does not guarantee repayment or compensation.
Worked example: completed without a receiving credit
Imagine a fictional 200-unit withdrawal entered on Monday and marked completed on Wednesday. By the following Monday, the receiving statement has no matching credit. A useful complaint asks what completion confirms, when release occurred and which reference the receiving institution can trace.
It should not assume the Wednesday status change proves a bank transfer happened then. Nor should it combine the platform request number with a payment-network reference as if they were interchangeable. Ask for the missing evidence rather than guessing the failed stage.
If a charge is disputed, calculate it separately. A 200-unit request and 196-unit receipt show a four-unit difference, equivalent to 2% of the requested amount. That arithmetic does not establish whether the deduction was permitted; the applicable tariff and payment records are still needed.
Broker withdrawal complaint template
Subject: Formal complaint — withdrawal [ID], [amount/currency]
I am complaining about withdrawal [ID], submitted on [date/time/timezone] using [method]. My agreement identifies [entity]. The current status is [status].
The relevant guidance states [brief accurate description, with document/date]. The unresolved issue is [specific difference between the obligation and observed events]. My chronology is [submission, document completion, status changes and follow-ups].
I request [release status and trace reference / explanation of restriction / fee breakdown / correction and reconciliation]. Please acknowledge this complaint, provide a case number and identify the applicable complaint timetable. If the issue is not resolved, please provide a written final position and the relevant external escalation information.
Evidence: [indexed relevant attachments]. I can provide sensitive records through a verified secure channel.
Tailor the template to the actual facts. Do not claim an unauthorised transaction if you authorised it, or demand a refund of trading losses as though they were an unpaid withdrawal. Those are different disputes.
Choose the right escalation route
A provider’s complaints department, a bank’s payment investigation, a regulator, an ombudsman and a crime-reporting service perform different functions. More than one route may be relevant, but eligibility and deadlines must be checked independently.
| Route | What to verify |
|---|---|
| Provider formal complaint | Genuine contact channel, responsible entity and documented timetable. |
| Bank or payment provider | Trace, fraud report or dispute options for the actual transaction. |
| Regulator or ombudsman | Entity, product, customer location and complaint eligibility. |
| Crime-reporting authority | Appropriate jurisdiction and evidence of suspected fraud. |
For eligible UK matters, the FCA describes complaining to the firm first and generally an eight-week outcome period, with different rules for certain payment-service complaints. It directs eligible customers towards the Financial Ombudsman Service and notes a six-month period after a final response. These are scoped UK instructions, not a deadline for every offshore broker.
In India, SCORES describes securities-market grievances against listed companies, SEBI-registered intermediaries and market infrastructure institutions. Its FAQ excludes unregistered or unregulated activity from that complaint mechanism. Do not assume an offshore binary platform is covered merely because an Indian resident used it.
For suspected cyber financial fraud in India, SEBI’s fake-app awareness material points to the national cybercrime portal and 1930. Report promptly and contact the relevant payment institution; do not wait through an ordinary complaint timetable if an active fraud or unauthorised-payment situation requires immediate action. Reporting does not guarantee recovery.
Bank disputes and legal deadlines need case-specific advice
Ask the bank or card issuer what options apply to your actual payment and when evidence must be supplied. Eligibility can depend on transaction type, authorisation and other facts. Do not copy a universal chargeback deadline from an unrelated case.
If formal legal action is being considered, obtain advice appropriate to the entity, contract and jurisdiction. Preserve any final response and filing dates. This guide organises evidence; it does not determine your legal entitlement or limitation period.
Avoid turning a withdrawal problem into a second loss
The FCA warns that recovery-room fraudsters approach people who lost money, promising recovery for upfront charges and sometimes impersonating authorities. Verify any proposed representative independently before sharing evidence or paying.
Passwords, one-time codes, private keys and remote access are not necessary to write a complaint. A professional-looking recovery website or a claim to know the exact lost amount does not prove legitimacy.
Frequently asked questions
Should I complain to every regulator at once?
Check remit first. A clear submission to the relevant organisation is more useful than unsupported claims sent to unrelated bodies.
Does a complaint guarantee a refund?
No. Evidence, applicable rules, jurisdiction and the outcome of the investigation determine the available remedy.
Can I publish the complaint publicly?
Keep statements factual and redact identity and payment details. A public post does not replace the formal process or preserve every deadline.
Official sources and related guides
- FCA complaint guidance and recovery-room warning.
- SCORES scope and exclusions.
- SEBI fake-app awareness material and reporting routes.
Related: Withdrawal research hub · Pocket Option withdrawal · Quotex withdrawal · Research methodology.
Scope: Checked 24 October 2026. Educational evidence organisation, not legal advice or a promise of repayment.