


We may earn a commission through these partner links. Demo funds are virtual; access and country eligibility depend on the platform terms. Disclosure
A difference between the trading-account owner and payment-source owner can create a funding or withdrawal problem. Resolve the identity facts through the genuine process rather than altering records to make them appear consistent.
Identify which names differ
Compare the account’s legal owner, payment account holder, transaction recipient and identity-document name. A payment processor’s descriptor can also differ from the consumer-facing brand, so record roles carefully.
Do not assume every difference has the same cause. A typo, surname change, business account and another person’s card represent different situations.
Read the provider’s ownership rule
Pocket Option’s published payment wording refers to customer-owned funding sources. Other providers apply their own requirements and exception processes.
This is a reason to inspect the actual account’s terms, not a universal claim that every mismatch produces the same penalty. Obtain a specific written explanation if a payment is restricted.
A correction worksheet
| Situation | Appropriate enquiry |
|---|---|
| Profile typo | Official correction process |
| Genuine name change | Accepted supporting records |
| Another person funded it | Documented handling or return route |
| Unknown statement descriptor | Payment reference and recipient identification |
| Wrong account selected | Trace and account-credit investigation |
Do not edit the evidence
Keep original statements and identity documents. If the account information is wrong, ask for the genuine correction process instead of modifying the document image.
Do not create a duplicate account under another identity or relabel a third-party payment as your own. A workaround can create further ownership and recovery problems.
Preserve the payment trace
Record transaction ID, date, amount, currency, source ownership and account credit. Share full identifiers only through verified appropriate channels.
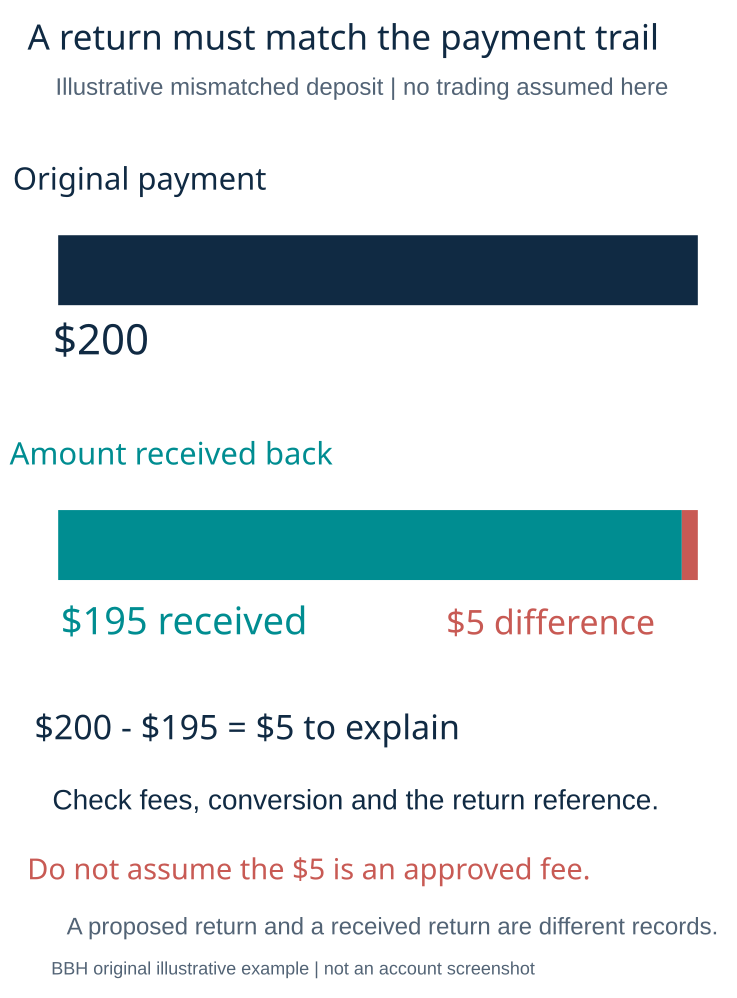
If the provider proposes returning the payment, ask which destination, amount and reference will be used. Keep the return separate from any trading result and reconcile it against the receiving statement.
Know what resolution would establish
Correcting a name mismatch can resolve that operational issue. It does not prove the product is suitable, that a provider is authorised locally or that every future withdrawal will succeed.
If the explanation remains unclear, request the applicable clause and complaint route. Document the unresolved requirement rather than guessing which additional payment or trade would remove it.
Same person, different spelling: establish the connection
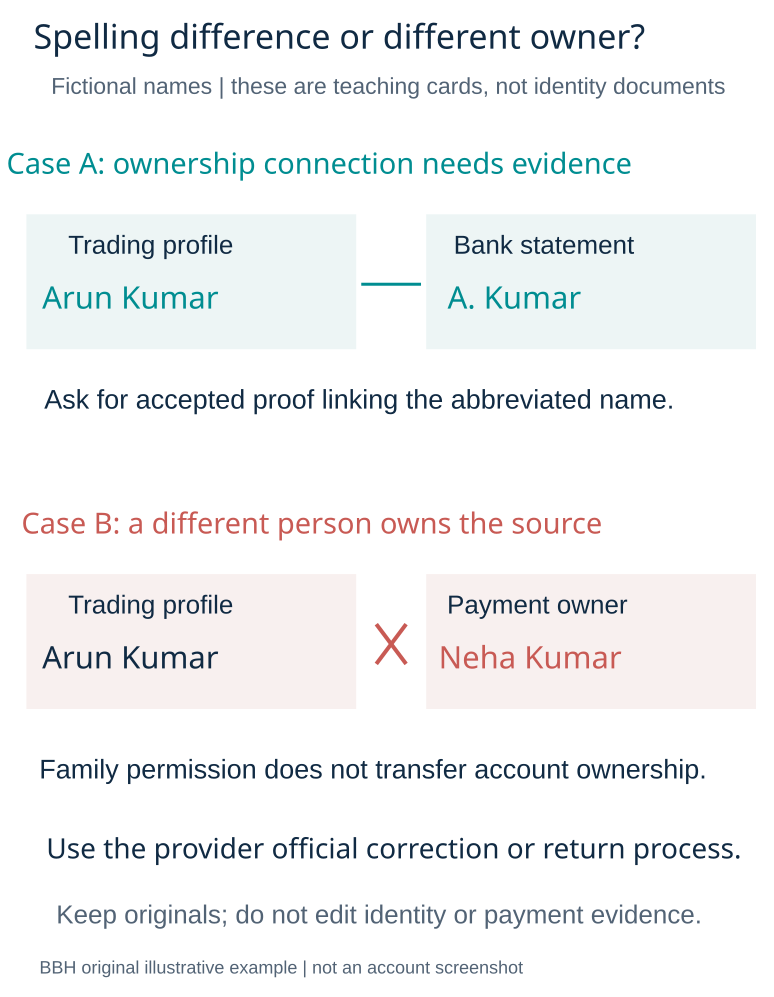
A missing middle name, changed surname or transliteration difference may concern one person. A payment made from a relative’s account concerns another owner. Those cases need different explanations even if both trigger a name check. Do not assume that a visual similarity between names proves ownership, or that a spelling difference proves wrongdoing.
Write down the exact name shown on the trading profile, identity document and payment account. Keep the original spelling and script. If the bank abbreviates a name on its statement, ask what official ownership confirmation it can provide. The provider decides which evidence it accepts; this worksheet is not a guaranteed document checklist.
Illustrative cases and the question to ask
| Example | What remains uncertain | Useful next question |
|---|---|---|
| “A. Kumar” on a statement, full legal name on ID | Whether the abbreviated account belongs to the customer | Will an official bank ownership letter establish the link? |
| Old surname on the payment account | Which records connect the two names | Which genuine name-change documents are accepted? |
| Spouse’s card used with permission | Whether third-party funding is permitted | What documented return or review process applies? |
| Company account funds an individual profile | Whether the product accepts that ownership structure | Is this account type eligible for that source? |
Permission from a family member does not itself make their account your property or satisfy a platform’s funding terms. Likewise, an authorised card user and the payment-account owner may be distinct roles. State those roles accurately rather than changing the profile to match the card.
Provider examples: read the exact clause
Pocket Option’s payment policy says transaction sources must belong exclusively to the client and separately describes bank withdrawals to an account in the client’s name and electronic withdrawals to a personal wallet. Its wording should be read in full, including any method-specific provisions. Deriv’s funds-and-transfers terms prohibit sharing payment methods with another client and require withdrawals using the deposit method. These are examples from different providers, not a single universal rule or an endorsement of either service.
Before sending more funds, ask support to identify the applicable clause, the account restriction and the available resolution. A successful profile correction does not necessarily approve an already disputed deposit or release a withdrawal. Ask for each issue’s status separately.
Track a return without losing the payment trail
For an illustrative $200 mismatched deposit, record the original $200 payment, whether the account received credit, any trading activity and the amount proposed for return. If $195 arrives, the $5 difference needs an explanation supported by the applicable terms and payment records. Do not assume it is a standard fee, a missing profit or proof of fraud. Record conversion rates and currencies where relevant.
- Use the genuine logged-in support route and retain a case number.
- Ask which records establish ownership and which details may be masked.
- Keep unaltered originals; use only accepted secure submission channels.
- Obtain the return destination, currency, amount and transaction reference.
- Confirm receipt against the source owner’s statement and retain the resolution.
Never send passwords, one-time codes or card security codes to a support contact. Avoid posting identity or full payment details in public comments. For related process checks, use the funding research hub and research methodology.
Deposit name mismatch FAQs
Will changing my display name fix the mismatch?
A display label does not establish legal identity or payment ownership. Ask about the official profile correction and verification process.
Can I withdraw to a friend while my bank details are reviewed?
Do not assume that route is allowed. Ask for an approved handling process under the actual account terms rather than introducing another ownership mismatch.
Does a mismatch automatically mean the money is lost?
No single outcome follows from the label alone. The provider’s terms, payment status and ownership evidence matter. Obtain a written explanation and escalate unresolved issues through the relevant complaint route.
Sources and research scope
- Pocket Option payment policy: source ownership and verification
- Deriv: funds, transfers and payment-method restrictions
Public-source review: 25 October 2026. Examples are illustrative. Documentary research does not represent funded-account testing. Rules must be checked against the current product, entity and customer location.
Related research
Funding research hub · Research methodology · Calculation tools
Risk: Fixed-outcome contracts can lose the entire stake. No chart pattern, calculator or demo result guarantees future returns.