


A withdrawal marked pending, approved or completed describes a step in a provider’s workflow. It does not automatically establish that money has reached your bank or wallet. To understand a delay, identify the event behind the label and match it with evidence from the receiving account.
This guide provides a diagnostic framework rather than a universal dictionary. We checked official Binomo and Olymptrade examples on 24 October 2026. Other providers, payment methods and app versions may use different labels.
What withdrawal pending, approved and completed can mean
| Label | Possible event | Evidence to seek |
|---|---|---|
| Requested/submitted | The instruction entered the system. | Request ID, time, amount and destination. |
| Pending/under review | A queue, check or requirement remains. | Specific outstanding task and next review step. |
| Approved | Authorisation or hand-off to a payment provider. | Whether external release actually occurred. |
| Processing | The platform or a downstream provider is working on it. | Which organisation currently holds the task. |
| Completed/sent | The provider considers its stage finished. | Release details and a suitable external payment reference. |
| Rejected/cancelled | The request will not proceed in its current form. | Recorded reason and any balance reversal. |
| Received/credited | The destination recorded the payment. | Receiving statement and matched amount. |
The useful question is “What changed when this label appeared?” A green tick can confirm an internal operation without confirming final credit. Conversely, a receiving credit may appear before a delayed interface refresh. Reconcile the records instead of relying on colour or wording alone.
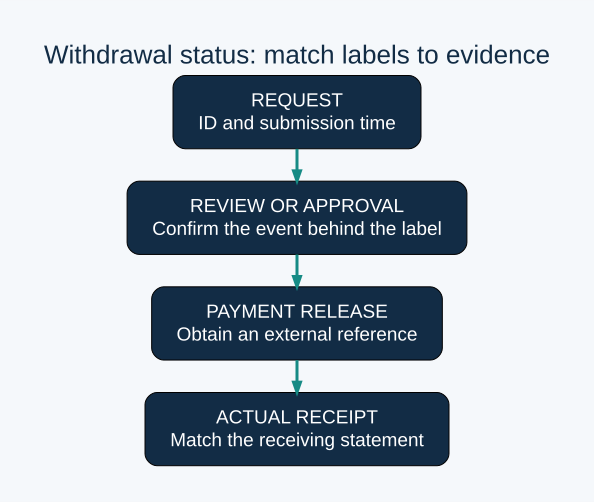
Official examples: why one status dictionary is insufficient
Binomo’s timing help page says a new request is “Approving”, or “Pending” in some mobile versions. After approval and hand-off, it is “Processing”, or “Approved” in some mobile versions. That illustrates how an identical operational stage can have different names across interfaces.
Olymptrade’s withdrawal FAQ discusses completed card withdrawals that have not yet arrived. It says an ARN can be requested through its chatbot after three working days without receipt. This is a concrete example of completion and receiving credit being separate facts; the threshold is that provider’s guidance, not a universal banking rule.
Our interpretation is therefore to keep three questions distinct: was the request accepted, was money released, and was money credited? The official examples support that distinction, but do not prove the cause of an individual delay.
Record the correct start event and day count
Imagine a request submitted Friday, approved Monday, released Tuesday and credited Wednesday. Friday-to-Wednesday is five elapsed calendar days when comparing the same clock time. Tuesday-to-Wednesday is one. Both can describe the same payment if their start events are stated.
Business-day claims require more information: which calendar applies, whether the submission day counts, what cut-off exists and whether a holiday intervened. Do not silently turn “five days” into “five working days”, or count from approval when the policy counts from submission.
Use a small chronology with event, timestamp, timezone and supporting record. Where a bank statement shows only a date, avoid inventing the hour. Keep an updated estimate separate from the original estimate so the history remains clear.
Why a withdrawal may remain pending
A pending status is an observation, not a diagnosis. Possible questions include whether identity review is incomplete, payment details need correction, a balance condition applies or the downstream provider has not accepted the instruction. Ask which of these, if any, applies to your actual request.
Check the account’s notices and document section before resubmitting files. A proof-of-payment request is different from an identity request. Preserve the full-submission date and rejection reason if a file needs correction; repeatedly sending an unsuitable document can obscure the record.
If support states that no customer action is outstanding, ask for the current stage and the applicable service period. “Please wait” becomes more useful when it identifies a specific review or transfer rather than an unexplained rolling deadline.
Completed but money not received: investigate release and receipt
- Confirm the request amount, currency and masked destination.
- Ask for the actual release time, rather than only the time the status changed.
- Obtain a reference appropriate to the payment network.
- Compare the receiving statement over the relevant date range.
- Ask the receiving institution to trace the reference if no matching credit exists.
For an eligible card transaction, an ARN may be useful. A bank transfer may use a different reference, and a blockchain transfer needs a transaction hash and network. An internal broker ticket number is not automatically searchable in an external payment system.
Do not assume a payment is on-chain merely because a crypto withdrawal shows completed. Establish whether it was broadcast and whether the receiving service has credited it. Likewise, a bank’s “not found” reply needs context: what reference and date range did it search?
Reconcile amount differences and rejected requests
Keep requested gross amount, account debit, amount sent, fees, conversion and receiving credit separate. In an illustrative 100-unit withdrawal with a two-unit fee, a 98-unit transfer may reconcile correctly. That example does not establish any provider’s actual fee.
For a rejected request, look for a matching reversal, not a new deposit. If the original debit remains unexplained, ask whether the balance is reserved, returned or still under investigation. Do not count the same reversal twice because it appears in both history and a balance screenshot.
A support template for an unclear withdrawal status
Withdrawal [ID] for [amount/currency] was submitted [date/time/timezone]. It changed from [old status] to [new status] on [date]. The destination is [method and masked identifier]. Please explain what event the current label confirms, any outstanding requirement, and the applicable processing period. If money has been released, please provide its release time, amount and appropriate external trace reference. My receiving statement currently shows [no credit/different amount].
Retain replies and case numbers in one chronology. Share sensitive records only through the appropriate secure channel and redact public copies. If the documented process fails, request the relevant entity’s complaint procedure with a clear statement of the unresolved fact.
Frequently asked questions
Does approved mean I can spend the money?
Only the destination’s available credit establishes spendable receipt there. Ask what approval means in the provider’s workflow.
Does pending mean fraud?
No. A label alone does not establish intent, cause, solvency or eventual outcome.
Should I cancel and request again?
First confirm whether cancellation is possible, whether a payment is already in flight and what happens to the original debit. A new request is not evidence of faster processing.
What does one successful withdrawal prove?
That particular transaction, when properly reconciled. It does not guarantee future payouts or establish regulatory permission.
Sources and related reading
Related: Withdrawal research hub · Pocket Option withdrawal · Quotex withdrawal · Research methodology.
Scope: Checked 24 October 2026. Diagnostic examples are educational and do not establish a universal payment deadline or independently verified provider performance. Additional deposits or trading are not a payment trace.